Updated October 29, 2026
Step by step
1. Report it. Call your agent or insurance company as soon as you can, with your policy number if you have it. You can report the claim before you are back in the house.
2. Keep a log. Write down every call: the date, the time, who you spoke with, the adjuster's name and what was said.
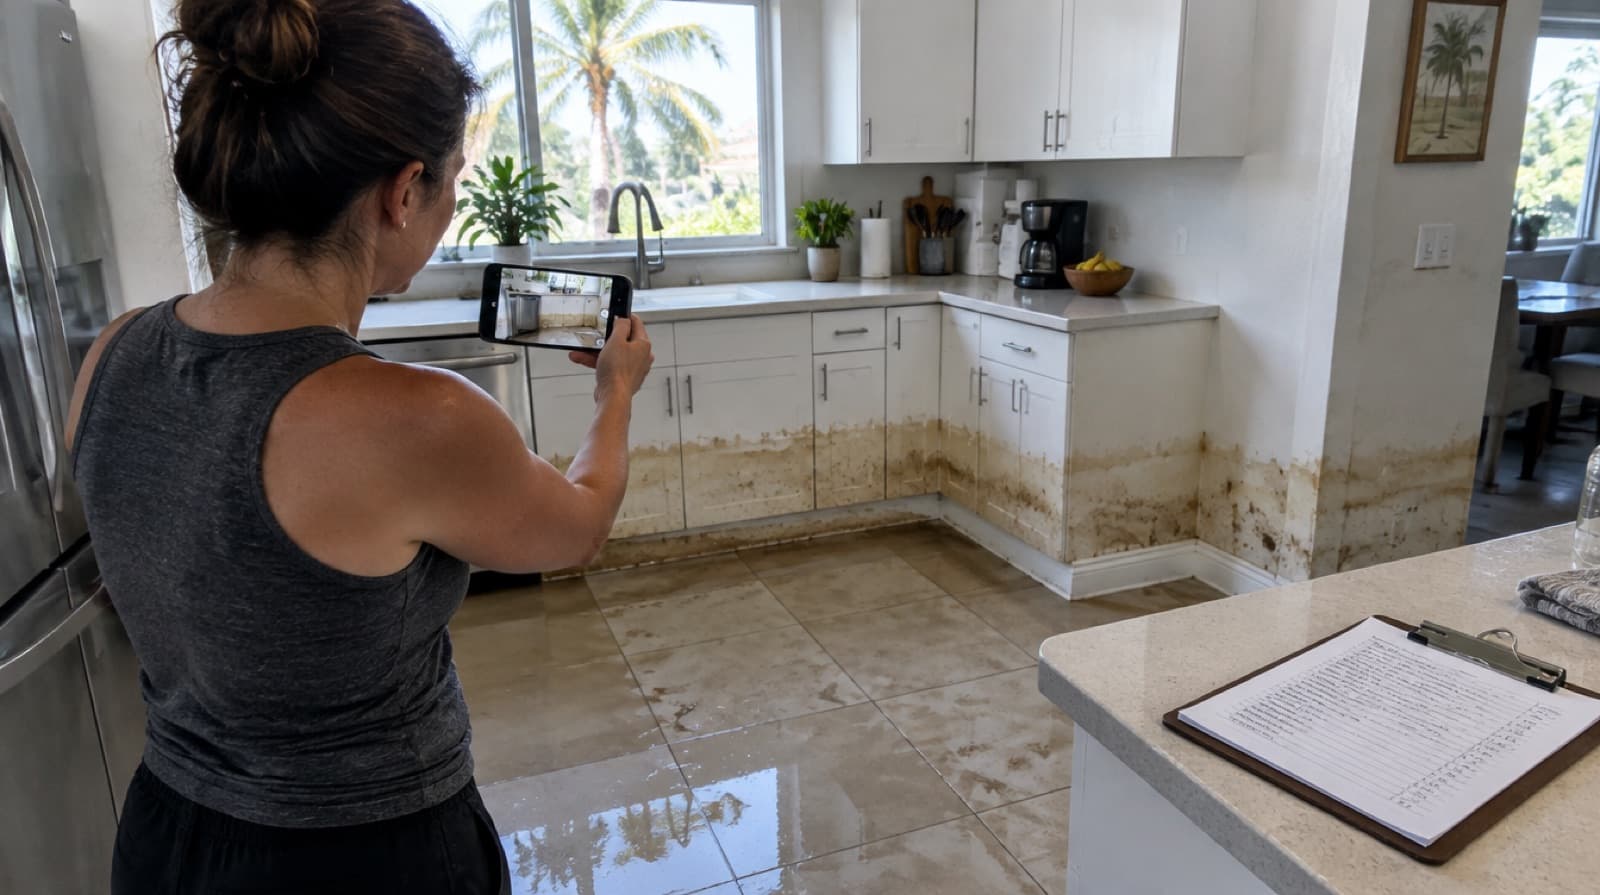
3. Document. Photograph and video the outside and inside of the house, the water line inside and out, and every damaged item. Get the make, model and serial number of appliances. For contents, list each item with a description, age, quantity and replacement cost.
4. Separate and keep samples. Move damaged things away from what was not damaged. If something has to go, keep a sample of the carpet, flooring or blinds for the adjuster.
5. Start safe cleanup. The checklist says not to throw anything away before the adjuster sees it unless it is a health hazard. FEMA's flood repair guide treats drywall soaked by floodwater as a health hazard, so photograph it, keep a piece, and ask your carrier before you hold off on drying.
6. Send your documentation within 60 days of the flood, or by the deadline your adjuster gives you.
When the adjuster comes
Ask to see the adjuster's Flood Control Number card and a government photo ID. Give them your photos, video and lists. You can ask for an advance partial payment. When the estimate comes, read it line by line against what you saw in the house, and ask them to correct anything missing or wrong.
If you find more damage later, or the repair costs more than the estimate, you can request an additional payment at any time, even after the claim seems settled. If the claim is denied, you can appeal to FEMA within 60 days of the denial letter. All of this comes from the NFIP checklist. Private flood policies set their own rules, so read yours, and see what flood insurance covers.
Related questions
Can I start drying the house before the adjuster comes?
In most cases you should start protecting the house, as long as you document first. The NFIP checklist tells policyholders to ask their insurer which cleanup costs are covered and to begin cleanup safely, while not throwing items away before the adjuster sees them unless they are a health hazard. FEMA's own repair guide treats drywall soaked by floodwater as a health hazard, and in a South Florida house wet drywall, carpet and pad start growing mold within a day or two. So the order is: photograph and video every room, measure and write down the water line, keep a cut sample of each wet material, then remove it and start the dehumidifiers. Call your carrier first and ask if they want anything held. Keep receipts for drying equipment and emergency work. And remember that NFIP coverage excludes mold the owner could have avoided, which is one more reason not to wait.
What if the adjuster's estimate is too low?
First, compare it room by room with what you know was damaged. Common gaps are the height of the drywall cut, insulation, baseboards, cabinet bases, closets, door casings and the cost of drying equipment. Write down anything missing and send it to the adjuster with photos. The NFIP checklist says you can ask them to correct mistakes, and you can request an additional payment at any time if you find more damage or the real repair cost is higher than the estimate, even after the claim looks settled. A written scope from the company doing the repair, broken out by room and by trade, makes that request much easier to support. We put one together for every flood job, and we answer the adjuster's questions about it. We do not negotiate the claim for you. If the claim is denied, the appeal goes to FEMA within 60 days of the denial letter.
Areas hit by the October tide
- King tide flood damage repair in Fort Lauderdale
- King tide flood damage repair in Hollywood
- King tide flood damage repair in Miami Beach
- King tide flood damage repair in Miami and Miami Shores
More questions
- When is the next king tide in Fort Lauderdale and Miami?
- What should I do after king tide water gets into my house?
- What is a flood cut, and how high should drywall be cut after a flood?
- How long does it take to dry out a house after a flood?
- How fast does mold grow after a flood, and how do I stop it?
- Does insurance cover king tide flooding?
- My garage flooded with saltwater. What do I do?
- Is it safe to stay in a house after flooding?
- How can I tell if my drywall has water damage after a flood?
- Are king tides getting worse in South Florida?
- Who do I call for water damage after a flood?
- Can water damaged kitchen cabinets be saved after a flood?
- Which flooring can be saved after a flood: tile, laminate, vinyl or wood?
Sources
- FloodSmart (NFIP), Claims checklist for policyholders
- FloodSmart (NFIP), What is covered by a flood insurance policy for homeowners
- FEMA P-234, Repairing Your Flooded Home (copy hosted by the National Center for Healthy Housing)
- Florida Department of Financial Services, Flood Insurance Coverage FAQs
The image on this page is an illustration, not a photo of one of our jobs.