Updated October 29, 2026
The 30-day wait and the November tides
FloodSmart, the NFIP's consumer site, says coverage goes into effect 30 days after purchase, with a few exceptions such as buying it while making, increasing, extending or renewing a mortgage. For example, a policy bought on October 29, 2026 would start on November 28. It would not be in force for the November 5 to 11 window or most of November 22 to 28, but it would be for December 24 to 25 and the 2027 season.
If you have a flood policy now
Report the loss to the company that wrote the policy right away. Florida's Department of Financial Services says you must file a signed proof of loss within 60 days of the date of loss, and lists the NFIP at 877-336-2627. Building coverage and contents coverage are separate under the NFIP, so check which you have. Document before you remove anything, and keep receipts for drying equipment and emergency work. Our step by step claim guide covers the rest.
What flood insurance covers and what it does not
Under the NFIP, building coverage pays for the structure and foundation, plumbing and electrical systems, central air and heating, and attached cabinets, bookcases, carpet and paneling. Contents coverage pays for clothing, furniture, electronics, curtains, washers and dryers, and freezers and the food in them. Building coverage tops out at $250,000 and contents at $100,000, according to FloodSmart.
It does not cover temporary housing while the house is repaired, property outside the building like seawalls, decks, fences and pools, cars, or moisture and mold damage the owner could have avoided. That last one is why drying in the first 48 hours matters for your claim, not just for your walls.
Related questions
My homeowners policy covers water damage. Why doesn't it cover this?
Because insurance separates water damage by where the water came from. A homeowners policy usually covers sudden water from inside the house, like a burst supply line or a water heater that fails. It usually excludes flood, which is water that rises from outside and covers normally dry land, whether it comes from rain, storm surge or a king tide coming over a seawall and up through storm drains. That exclusion is the reason the National Flood Insurance Program exists. There are gray areas. Water that backs up through a sewer line or floor drain can be its own category with its own coverage or exclusion. And in a king tide, rain often falls at the same time. Read the definitions in your own policy, describe exactly how the water got in when you report it, and let the adjuster classify it. Do not guess at the cause on the phone. Describe what you saw.
What do you give me for my insurance claim?
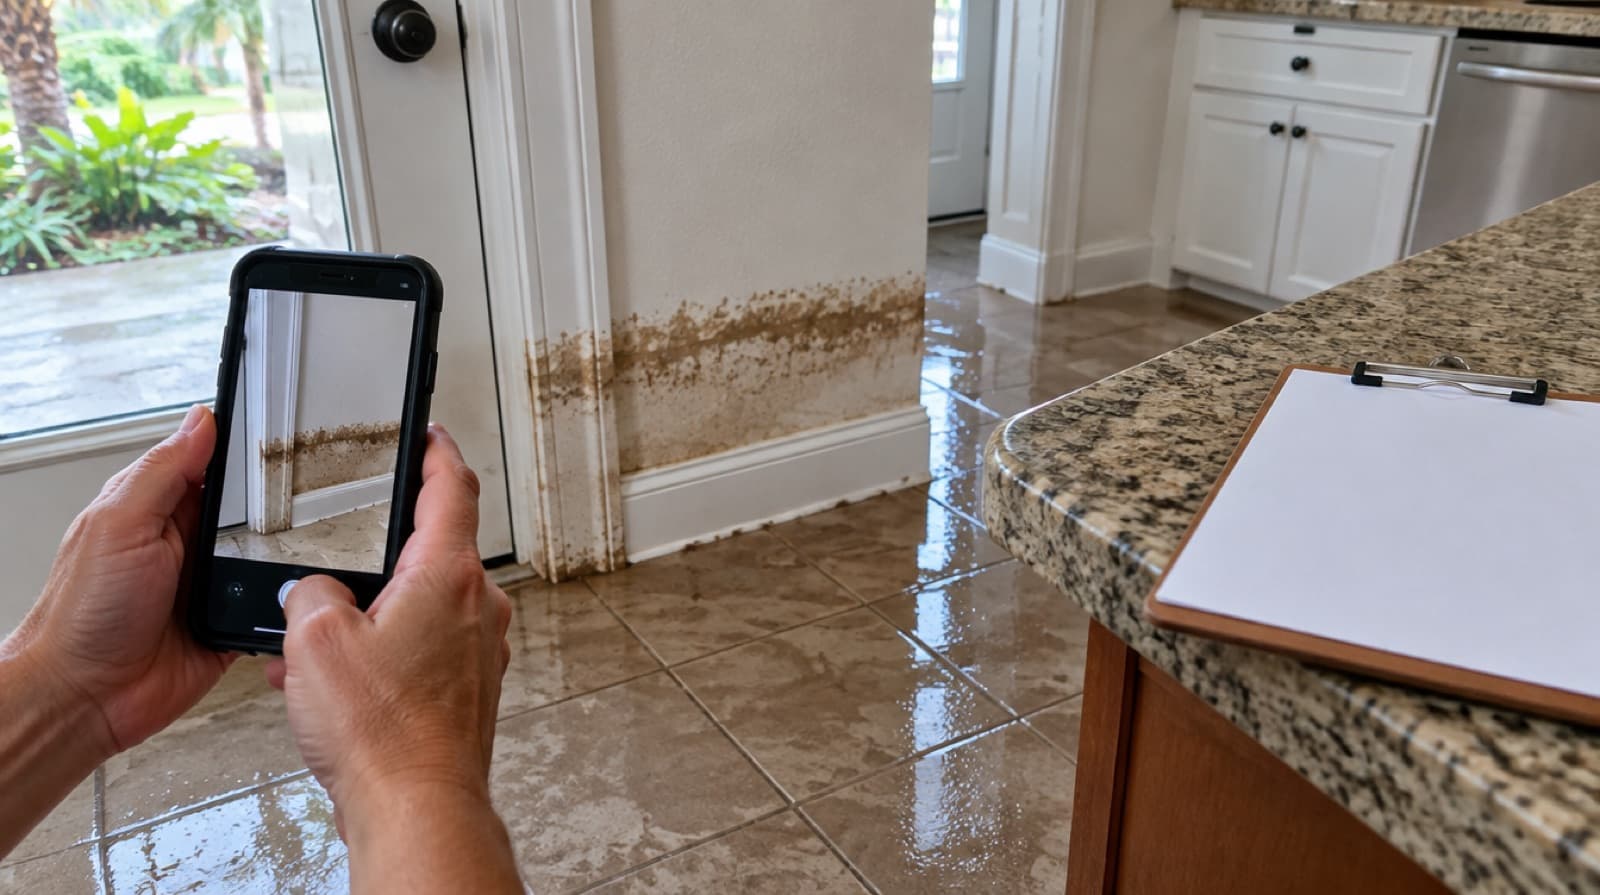
We give you the paperwork that shows what happened and what the repair is. That means dated photos of each room before and during the work, the height of the water line and how far the wet reached up the walls, a list of what was removed, and a written scope of the repair broken out by room and by trade: tear-out, drying, drywall, paint, flooring, baseboards, cabinets, and anything else the water reached. If the adjuster asks questions about the scope, we answer them. What we do not do is negotiate your claim or act on your behalf with the insurance company. That relationship is between you, your carrier and your adjuster, and if you want someone to represent you in the claim, that is a different kind of professional. Our job is to give you clear, honest documentation and then do the repair well.
Areas hit by the October tide
- King tide flood damage repair in Fort Lauderdale
- King tide flood damage repair in Hollywood
- King tide flood damage repair in Miami Beach
- King tide flood damage repair in Miami and Miami Shores
More questions
- When is the next king tide in Fort Lauderdale and Miami?
- What should I do after king tide water gets into my house?
- What is a flood cut, and how high should drywall be cut after a flood?
- How long does it take to dry out a house after a flood?
- How fast does mold grow after a flood, and how do I stop it?
- My garage flooded with saltwater. What do I do?
- Is it safe to stay in a house after flooding?
- How can I tell if my drywall has water damage after a flood?
- Are king tides getting worse in South Florida?
- Who do I call for water damage after a flood?
- How do I file a flood insurance claim after the king tide?
- Can water damaged kitchen cabinets be saved after a flood?
- Which flooring can be saved after a flood: tile, laminate, vinyl or wood?
Sources
- FloodSmart (NFIP), Policy terms and the 30-day waiting period
- FloodSmart (NFIP), What is covered by a flood insurance policy for homeowners
- FEMA, Flood Insurance
- Florida Department of Financial Services, Flood Insurance Coverage FAQs
- City of Fort Lauderdale, King Tides and High Tides
The image on this page is an illustration, not a photo of one of our jobs.